Europe wants European PCBs – the question is who commits first
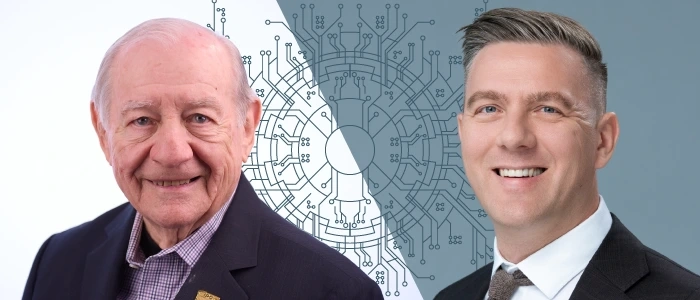
Europe says it wants its PCB industry back. But when Vytautas Ilgūnas, CCO of TLT PCB, asks whether customers actually mean it, industry veteran Gene H. Weiner’s answer is blunt: “They say yes, but behave no.” Ilgūnas himself sees a European market that has started to move – though not everywhere at the same speed.
For the past several years, the European electronics industry has been discussing the decline of PCB manufacturing in Europe – and the urgent need to do something about it. Dieter G. Weiss, as well as Evertiq, has repeatedly reported that Europe today accounts for less than 2% of the global PCB market. In less than 25 years, and without any coherent regional strategy, Europe has lost much of its capacity in a technology that is fundamental to virtually every part of the electronics industry.
But does Europe really understand the need for change, and is it actually prepared to make it happen? Or are we still mainly dealing with slogans about European resilience, strategic autonomy and the need to rebuild local manufacturing – without actual backing? Because if Europe truly wants to bring PCB manufacturing back, there is one rather simple question that needs to be asked: where are the orders?
That question runs through an exchange between Gene H. Weiner, a veteran of the global PCB industry, and Vytautas Ilgūnas, CCO of TLT PCB – the company behind one of Europe’s newest PCB factories. Ilgūnas asks the questions; Weiner answers. But Ilgūnas has answers of his own, and they do not always match Weiner’s.
Much of the difference comes down to where they stand. Weiner looks at the Western market as a whole and sees a persistent gap between what customers say and what they buy. Ilgūnas sees European customers from the commercial side of a new European factory – and what he sees is reshoring beginning to move from discussion into action. Between them, they describe both the gap between Europe’s ambitions and the reality on the ground, and what it will take to close it.
The biggest barrier is not factories – it is customers
Ilgūnas opens with a question that strips away the policy language: if you were investing your own money, where would you build?
For Weiner, the answer is still the West – but not at any cost.
“If I were investing my own money today, I would build in North America or Europe, but only for markets where customers already show willingness to pay a premium: defence, aerospace, medical, industrial controls, energy, and high-reliability computing.”
Just as telling is where he would not compete: commodity PCBs, consumer electronics, and production dependent on high-end AI-server CCLs – unless backed by guaranteed long-term commitments.
It strikes me that his answer is not really about geography at all. It is about customers. And Weiner soon says so outright.
“The biggest barrier is not factories – it is customers unwilling to commit.”
For years, much of the debate has focused on capacity: how much Europe has lost, how much needs to return and what investment it would take. But capacity cannot be rebuilt in isolation. A new PCB factory needs something more tangible than political declarations about resilience and autonomy. It needs orders.
As previously reported by Evertiq, TLT Manufacturing has been making headlines in recent years with its expansion strategy. In September 2025, the Lithuanian electronics group inaugurated a EUR 320 million expansion in Vilnius, which included four new factories – among them Europe’s first new PCB factory in 20 years – highlighting its ambition to build a vertically integrated manufacturing park in Europe.
They say yes, but behave no
Ilgūnas then goes straight to the contradiction at the centre of the debate: do Western customers genuinely want Western manufacturing?
Weiner’s reply is short enough to fit in a headline.
“They say yes, but behave no. Western OEMs talk about resilience and security of supply, but when sourcing decisions are made, price dominates.”
Customers want Western supply in theory, he argues, but in practice still expect Asian pricing. And without long-term commitments from those customers, manufacturers have little basis on which to justify new capacity investments.
Manufacturers, Weiner argues, cannot invest in new Western factories unless customers sign multi-year, volume-secured contracts.
That does not necessarily mean fixed prices. Weiner has had to add or pay surcharges in the past when the cost of raw materials such as palladium or certain resins rose rapidly. One solution, he says, was to tie future price adjustments to an index of the relevant commodities or a group of related materials, reviewed quarterly or semiannually.
Not every part of the market behaves the same way. There are sectors genuinely prepared to pay for Western manufacturing. Beyond the premium sectors he named earlier, Weiner adds – more selectively – telecom infrastructure and automotive safety systems in Europe. Consumer electronics and commodity computing are a different story. So, he says, are AI server OEMs: despite enormous demand, their sourcing remains concentrated in Asia because of cost and material availability.
In Weiner’s reading, the conclusion is unavoidable. If Western customers want a local PCB industry, they have to support it through their sourcing decisions. Resilience may be a strategic objective, but without contracts, volumes and prices that make local production viable, it remains just that – an objective.
Some customers have started to act
Ilgūnas agrees that purchasing decisions are what ultimately decide whether reshoring succeeds. But from where he sits, part of the European market is already changing its behaviour.
“In Europe, reshoring is no longer only a discussion. We already see major EMS companies and OEMs qualifying local suppliers, placing orders and discussing multi-year capacity commitments,” he says.
That does not mean Europe has rebuilt the ecosystem it lost, and Ilgūnas does not claim it has. Defence, aerospace, industrial and other high-reliability sectors are leading, he says – largely the same sectors Weiner identified as willing to pay a premium. Meanwhile, large EMS companies and OEMs are increasingly treating local capacity as something that has to be secured in advance. The pace, however, varies considerably from one customer to the next.
“The change is visible, but it is not happening everywhere at the same speed. Some customers are already planning several years ahead. Others still approach European capacity only when they have an immediate requirement. By then, it may be too late to create the capacity they need.”
This is where the two perspectives meet. Weiner says manufacturers need multi-year, volume-secured commitments before they can invest. Ilgūnas says some customers have begun to provide exactly that – and that those who have not may be running out of time. An expression of interest does not allow a manufacturer to hire and train teams, secure materials or invest in new processes. Forecasts, supplier qualifications, orders and capacity planning do.
Timing matters, Ilgūnas points out, because PCB capacity cannot be switched on when a disruption begins. A new factory requires equipment, permits, process development, trained people, stable yields and qualified materials, and customer qualification alone can take months or years in regulated and high-reliability sectors. Companies that wait until demand becomes urgent, he warns, may find that the capacity they need has already been committed to someone else.
“Capacity is not elastic. We cannot stretch a factory when demand suddenly appears. If European supply is part of a company’s strategy for the coming years, qualification and capacity planning have to start now.”
If they want to survive, they have to act together
Ilgūnas then widens the lens. Asia benefits not only from manufacturing capacity, but from enormous scale and a deeply integrated supply chain. Can Europe and the US realistically compete while approaching industrial policy, investment and procurement as separate markets? Should they start acting as one PCB and electronics manufacturing ecosystem?
“Yes, I agree – if they want to survive,” Weiner says.
He outlines three steps. The first is the most ambitious: a single US–EU–UK Electronics Council to coordinate incentives, materials and substrate strategies, export controls, OEM commitments, supply-chain security and R&D funding. The Council would treat materials as strategic assets, divide manufacturing roles, build shared R&D and negotiate as one bloc with Japan and Taiwan. Above all, it would aim to create something Western PCB manufacturing currently lacks: scale comparable to Asia.
“This is the most logical – but probably unlikely to happen – path to rebuilding Western PCB, CCL and substrate manufacturing.”
The underlying argument, though, is hard to dismiss. If neither Europe nor the US has the scale to rebuild the ecosystem alone, treating them as separate markets only makes the task harder.
“The EU and the US have to synchronize their current chip and related policies,” Weiner says.
Without materials, there is no ecosystem
When Ilgūnas asks what else a genuine transatlantic ecosystem would require, the conversation turns to something far more tangible: materials.
Weiner’s second step is to “develop and scale a secure ecosystem with alternatives for all major materials needed for advanced packaging.” His third is closely connected: a rapid approval method for new materials capable of replacing those that become unavailable as demand from AI servers, power infrastructure and other applications grows.
The potential choke points are already identifiable. Weiner points to high-end CCLs, ultra-smooth copper foil and laminates using T- or Q-glass. Work on alternatives has begun, he notes, with companies developing substitutes for ABF build-up materials and glass-free technologies for HDI and UHDI.
But an alternative is only useful once it has been qualified and approved – and in Weiner’s proposal, that should ultimately mean unified standards across all members of the proposed Electronics Council.
Here, too, the conversation circles back to customers. Weiner points to Nvidia, Tesla and several other major OEMs and semiconductor companies that have made long-term commitments to suppliers – in some cases investing in them directly or promising funding. It is exactly the kind of commitment he said was missing earlier.
Further upstream, he singles out privately owned Principal Mineral, which, he says, has acquired and expanded the last copper foil company in the US and recently acquired Isola, a multi-facility CCL producer with a prepreg treating operation in the country.
These developments matter because rebuilding Western manufacturing is not simply a matter of opening new PCB factories. The materials, suppliers, qualification processes and hands-on know-how have to exist around them – and none of that appears overnight.
“A five-year action plan is needed. It takes several years to build the infrastructure needed and develop the hands-on know-how,” Weiner says.
Back to the orders
By the end of the exchange, I find myself back where I started – but with a different question. Weiner’s roadmap is coherent: coordinate across the Atlantic, secure the materials, qualify alternatives quickly and commit to a five-year horizon. Yet almost every step depends on someone else acting first. The Council is one he himself calls unlikely. New materials need customers willing to qualify new suppliers. And new factories need customers who, in Weiner’s words, too often say yes but behave no.
Ilgūnas answers that some of them have stopped waiting. How broad that shift is remains difficult to judge from the outside. But if he is right, the gap Weiner describes is not closing evenly across the market. It is closing customer by customer – and capacity will go to those who commit first.
“Reshoring will not happen through one announcement or one factory. It will happen through thousands of sourcing decisions. The companies making those decisions now will shape the European supply chain that exists five years from today,” Ilgūnas says.
So the question has shifted. It is no longer only whether anyone intends to buy from a rebuilt European PCB industry. It is who will buy early enough to secure the capacity – and who will start looking only after it has been committed elsewhere.