
AI keeps memory prices climbing in Q4 as consumer demand weakens
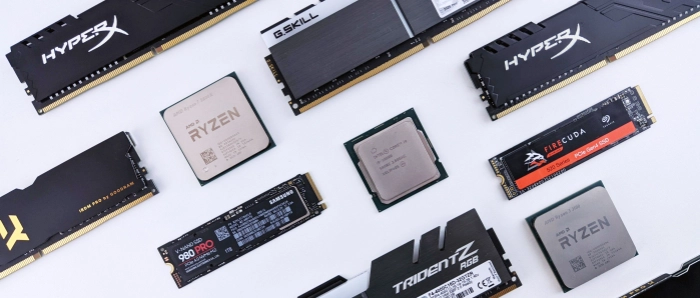
Contract prices for conventional DRAM are expected to rise by 10–15% QoQ in the fourth quarter of 2026, and NAND flash prices by 15–20%, according to TrendForce. AI servers continue to drive the market, while consumer electronics are increasingly struggling to absorb higher costs.
DRAM suppliers continue to prioritise advanced-process capacity for high-performance server products, keeping the overall market undersupplied, according to a press release from TrendForce. The pace of price increases is expected to moderate, however, partly because substantial increases were already priced in during previous quarters.
Server DRAM is expected to remain undersupplied. Improving CPU availability has prompted cloud service providers (CSPs) and server makers to step up purchasing of RDIMMs for general servers running agentic AI workloads. At the same time, constraints in components, packaging and test capacity, and front-end production continue to prevent supply from keeping pace. For some suppliers, price increases are expected to lag the market average because of pricing mechanisms in long-term agreements.
The consumer side is under growing strain. Higher memory costs are already weighing on notebook sales and smartphone production, and PC brands are reducing SSD capacities in mainstream models to lower bill-of-materials costs. Smartphone makers are largely relying on existing inventories of eMMC and UFS, and are buying only the minimum volumes needed to maintain supplier relationships. In the NAND flash wafer market, prices have reached historical highs that retail channels are increasingly unable to absorb, prompting module makers to buy more cautiously.
Enterprise SSDs stand out as the only memory category in which price growth is expected to accelerate compared with the previous quarter. TrendForce projects bit demand to grow by more than 80% YoY in 2026 as CSPs expand AI inference infrastructure, and most of the additional supply has already been committed, leaving little on the open market.
The capacity shift towards servers is also expected to have consequences next year. PC makers continue to buy aggressively in anticipation of tight supply in 2027, and TrendForce notes that PC DRAM supply could decline as more capacity moves to server applications.
| 3Q26 (E) | 4Q26 (F) | |
| Total DRAM | Conventional DRAM: up 13~18% HBM Blended: up 8~13% | Conventional DRAM: up 10~15% HBM Blended: up 15~20% |
| Total NAND Flash | Up 18~13% | Up 15~20% |